|
QUESTION
|
ANSWER
|
SECTION
|
|
About the Demerger
|
1. What is the
Demerger? |
Ramsay is proposing to distribute all of Ramsay Group's 52.79% shareholding in Ramsay Santé to Ramsay Shareholders on a pro rata basis, by way of an in-specie distribution implemented through a scheme of arrangement. If the Demerger is approved and implemented, Ramsay Shareholders will hold separate investments in Ramsay (post Demerger) and Ramsay Santé.
|
See the 'How it Works' Section of the Demerger Booklet for further information
|
|
2. Why is the Ramsay Board proposing the Demerger?
|
Following a comprehensive strategic review, including market testing of potential alternatives, the Ramsay Board concluded that the Demerger recognises the different geographic focus, strategies and capital profiles of Ramsay and Ramsay Santé, and should allow each company to pursue a more focused strategy and, over time, deliver greater value to Ramsay Shareholders than the current structure.
|
See the Chairman’s letter and Section 1 of the Demerger Booklet for further information
|
| 3. What are the key advantages of the Demerger? |
The key advantages of the Demerger include:
- Ramsay Shareholders will have greater flexibility and liquidity to choose their level of investment in Ramsay and Ramsay Santé;
- simplification of Ramsay’s reported financial profile through the full deconsolidation of Ramsay Santé from Ramsay’s financial statements;
- an improved ability for Ramsay and Ramsay Santé to each pursue independent growth strategies;
- enhanced management focus on the strategic priorities and performance of Ramsay’s Australian and UK operations; and
- the Demerger is the preferred method of separation relative to other alternatives, following a comprehensive strategic review and market testing the potential alternatives.
These advantages are discussed in Section 1.3 of the Demerger Booklet. Ramsay Shareholders should read Section 1.3 of the Demerger Booklet in its entirety before voting.
|
See Section 1.3 of the Demerger Booklet for further information |
| 4. What are the key disadvantages of the Demerger? |
The key disadvantages of the Demerger include:
- there will be approximately $59 million (pre-tax) in one-off transaction costs associated with the Demerger borne by Ramsay and Ramsay Santé, of which approximately $27 million will have been incurred prior to the Meetings (whether the Demerger proceeds or not), and certain ongoing costs for Ramsay Santé if the Ramsay Santé Securities are quoted as CDIs on the ASX;
- the Demerger will cause Ramsay to be smaller (in terms of revenue and number of hospitals) and less diversified than Ramsay immediately before the Demerger, although it will remain a significant entity with diversified operations and expected leverage within its target range of <2.5 times;
- some Ramsay Shareholders will not be eligible to receive Ramsay Santé Securities (and will instead receive cash proceeds from the sale of those Ramsay Santé Securities under the Sale Facility) or may be unable to retain Ramsay Santé Securities;
- CDI holders continuing to experience currency risk arising from movements in the AUD/EUR exchange rate;
- CDI holders having no assurance that an active and liquid trading market for Ramsay Santé CDIs will develop or be maintained on ASX following the Demerger; and
- as part of the Demerger, Ramsay Shareholders will exchange their indirect exposure to Ramsay Santé through Ramsay’s controlling 52.79% shareholding for direct, non-controlling minority holdings in Ramsay Santé. As a result, Ramsay Shareholders will no longer have the benefit of Ramsay’s controlling influence over Ramsay Santé’s strategic direction, governance, capital management or other corporate actions. Instead, Ramsay Shareholders will be exposed to decisions made by the Ramsay Santé Board, management and other significant shareholders, with a more limited ability to influence those outcomes.
These disadvantages are discussed in Section 1.4 of the Demerger Booklet. Ramsay Shareholders should read Section 1.4 of the Demerger Booklet in its entirety before voting.
|
See Section 1.4 of the Demerger Booklet for further information |
| 5. What are the potential risks associated with the Demerger? |
The main risks of the Demerger include:
- uncertainty about the market value of Ramsay Shares and Ramsay Santé Securities and stock market ratings following the Demerger;
- the potential for delays or unexpected costs in the implementation of the Demerger; and
- that the Court may not approve the Demerger or that the approval of the Court may be delayed.
These risks are discussed in Section 1.5 of the Demerger Booklet. Ramsay Shareholders should read Section 1.5 of the Demerger Booklet in its entirety before voting.
|
See Section 1.5 of the Demerger Booklet for further information |
| 6. What will the Demerger cost, and who bears it? |
The total transaction costs of the Demerger are estimated at approximately $59 million (on a pre-tax basis), of which approximately $27 million will have been incurred prior to the Meetings (whether the Demerger proceeds or not). These costs are borne by Ramsay (approximately $27 million in costs) and Ramsay Santé (approximately $32 million in costs). |
See Sections 1 and 2.5.4 and 4.11 of the Demerger Booklet for further information |
| 7. Will Ramsay Santé be adequately funded as a standalone company after the Demerger? |
Yes. Ramsay Santé already operates independently of Ramsay with its own Board, management team and standalone balance sheet, and its €1.75 billion senior debt and revolving credit facilities were fully refinanced in July 2026. This gives Ramsay Santé an established standalone capital structure and provides shareholders with visibility over its funding arrangements as an independent listed company. |
See the Chairman’s letter and Section 3 of the Demerger Booklet for further information |
| Board recommendation and Independent Expert |
| 8. What does the Ramsay Board recommend? |
Each Ramsay Director recommends that Ramsay Shareholders vote in favour of the Demerger Resolutions, and each Ramsay Director intends to vote all Ramsay Shares they control in favour of the Demerger Resolutions.
In relation to the unanimous recommendation of the Ramsay Directors, Ramsay Shareholders should have regard to the interests of the Group CEO & Managing Director, Ms Natalie Davis, in the outcome of the Demerger, as further described in Sections 4.6 and 8.2.1 of the Demerger Booklet.
Each Ramsay Director recommends that Ramsay Shareholders vote in favour of the Supplementary Award Resolution (subject to any abstentions noted in the Notices of Meeting), and each Ramsay Director intends to vote all Ramsay Shares they control in favour of the Supplementary Award Resolution (subject to any applicable voting exclusions).
|
See the Chairman’s letter and Section 1.1 of the Demerger Booklet for further information
|
|
9. What is the Independent Expert's opinion?
|
Deloitte Corporate Finance Pty Limited, the Independent Expert appointed by Ramsay, is of the opinion that, in the absence of a superior proposal, the advantages of the Demerger outweigh the disadvantages. Accordingly, the Independent Expert, has concluded that the Demerger is in the best interests of Ramsay Shareholders.
|
See Section 7 of the Demerger Booklet for further information
|
| About Ramsay Santé |
|
10. Who are the other shareholders in Ramsay Santé?
|
As at the date of the Demerger Booklet, Predica, a subsidiary of Crédit Agricole Assurances, has a 39.82% shareholding in Ramsay Santé, with the remaining 7.39% of Ramsay Santé Shares held by various other shareholders.
|
See Section 3.2.1 of the Demerger Booklet for further information
|
| 11. What will be Ramsay Santé’s strategy after the Demerger? |
Ramsay Santé’s strategic priorities are set out in Section 3.6 of the Demerger Booklet.
The future strategy of Ramsay Santé will ultimately be a matter for the Ramsay Santé Board and Ramsay Santé senior management to develop over time, and is subject to change or alteration as circumstances require. |
See Section 3.6 of the Demerger Booklet for further information
|
| 12. Who will be on the Ramsay Santé Board after the Demerger? |
The Ramsay Santé Board is expected to evolve so that, as from the implementation of the Demerger, it includes majority of independent directors, to reflect the post Demerger shareholding structure.
The five Ramsay nominated directors will resign from the Ramsay Santé Board following implementation of the Demerger.
The Ramsay Santé Board intends to appoint Frédéric Collet as Chair subject to his appointment as a director by the Ramsay Santé shareholders’ meeting to be held on 4 December 2026 and to implementation of the Demerger.
The Ramsay Santé Board also proposes that the Ramsay Santé shareholders’ meeting appoint Pascal Roché as an executive director and Alexandra Boleslawski as a Crédit Agricole nominated director, in each case subject to implementation of the Demerger.
|
See Section 3.7.1 of the Demerger Booklet for further information
|
|
13. Who will be on the senior leadership team of Ramsay Santé after the Demerger?
|
There are no expected changes to the senior management team of Ramsay Santé as a result of the Demerger, which is listed in Section 3.7.2 of the Demerger Booklet.
|
See Section 3.7.2 of the Demerger Booklet for further information
|
| 14. What are the potential risks of an investment in Ramsay Santé? |
Ramsay Santé will be subject to risks which may adversely affect its future operating or financial performance, or the investment return or value of Ramsay Santé Securities. Many of these risks are existing business risks, to which Ramsay Shareholders are already exposed, while others arise out of, or increase as a result of, the Demerger.
These risks are discussed further in Section 3.15 of the Demerger Booklet. You should review that section carefully before deciding whether or not to vote in favour of the Demerger. |
See Section 3.15 of the Demerger Booklet for further information
|
| Ramsay after Demerger |
| 15. In which stock market index will Ramsay be eligible for inclusion? |
It is likely that Ramsay will remain in the S&P/ASX 100 index based on the estimated free float adjusted market capitalisation as of 8 October 2026. Given that index inclusion depends on a number of factors, including trading performance of constituents, no assurances can be made regarding Ramsay’s index inclusion following the Demerger or in the future.
|
See Section 1.4.3 of the Demerger Booklet for further information
|
| 16. Who will be on the Ramsay Board after the Demerger? |
There will be no changes to the Ramsay Board as a result of the Demerger. Detailed biographies of the Ramsay Board can be found in Ramsay’s 2026 Annual Report or online at www.ramsayhealth.com.
|
See Sections 2.2.3 and 2.4 of the Demerger Booklet for further information
|
| 17. Who will be on the executive leadership team of Ramsay after the Demerger? |
There will be no changes to the Ramsay Executive Leadership Team as a result of the Demerger. Detailed biographies of the Executive Leadership Team (Australian/UK based) can be found in Ramsay’s 2026 Annual Report or online at www.ramsayhealth.com.
|
See Sections 2.2.3 and 2.4 of the Demerger Booklet for further information
|
| 18. What will be the impact of the Demerger on Ramsay’s dividends? |
Ramsay’s dividend policy will continue to be at the discretion of the Ramsay Board after the Demerger and may change over time. Decisions relating to dividend policy post Demerger will depend on Ramsay’s available franking credits, earnings, cash flows and target credit metrics. Notwithstanding this, Ramsay’s dividend policy is not currently expected to change.
|
See Section 2.5.8 of the Demerger Booklet for further information
|
| 19. What are the potential risks with respect to a continued investment in Ramsay post Demerger? |
Most of the risks factors currently faced by the Ramsay Group will continue to be faced by the Ramsay Group following the Demerger. Investors are already exposed to these risks through their investment in Ramsay, which are described in the Annual Report and available on the website.
|
See Section 2.6 of the Demerger Booklet for further information
|
| What you will receive |
| 20. What happens to my existing Ramsay Shares? |
Your existing Ramsay Shareholding is not affected by the Demerger. You will keep the same number of Ramsay Shares you hold at the Record Date; the Demerger gives you an additional, separate entitlement to Ramsay Santé Securities on top of your existing Ramsay shareholding.
|
See ‘How it works’ and Section 4 of the Demerger Booklet for further information
|
| 21. What will I receive if the Demerger is implemented? |
If you are an Eligible Shareholder (other than a Selling Shareholder), you will receive 0.25 of a Ramsay Santé Security for every one Ramsay Share you hold at the Record Date, rounded down to the nearest whole Ramsay Santé Security. Ineligible Overseas Shareholders will have their Ramsay Santé Securities sold under the Sale Facility. Small Shareholders will also have their Ramsay Santé Securities sold (unless they opt-out of the Sale Facility), as will the Ramsay Employee Equity Trust, which will elect to opt-in to the Sale Facility.
If you are a Small Shareholder (being those who hold 500 or less Ramsay Shares), you can elect to receive Ramsay Santé Securities rather than cash by submitting your Opt-Out Form so that it is received by Ramsay no later than 5.00pm (Sydney time) on 30 November 2026. Please see Section 4.9 of the Demerger Booklet for further details. |
See ‘How it works’ and Sections 4.1 and 4.9 of the Demerger Booklet for further information
|
| 22. Will I receive Ramsay Santé Shares or Ramsay Santé CDIs? |
You will receive Ramsay Santé CDIs if Ramsay Santé obtains an ASX Foreign Exempt Listing and quotation of Ramsay Santé CDIs on ASX and Ramsay elects for Ramsay Santé Securities to take that form. Otherwise, you will receive Ramsay Santé Shares, which trade on Euronext Paris in Euros.
To receive Ramsay Santé Shares, Eligible Shareholders (other than Selling Shareholders) will need to have or establish in advance an account with a participant able to receive and hold Ramsay Santé Shares on their behalf in Euroclear France. See Section 4.1 of the Demerger Booklet for further information.
Ramsay Santé has received in-principle approval from ASX for a Foreign Exempt Listing. As at the date of the Demerger Booklet, it is anticipated that Ramsay Santé Securities will be distributed in the form of Ramsay Santé CDIs.
The decision on whether the Ramsay Santé Securities take the form of Ramsay Santé CDIs or Ramsay Santé Shares will be communicated to Ramsay Shareholders by way of an ASX announcement before or after the Scheme Meeting. |
See Section 4.1 of the Demerger Booklet for further information
|
| 23. Do I need to pay anything to receive my Ramsay Santé Securities? |
No. Eligible Shareholders do not need to make any payment to receive their Ramsay Santé Securities and cannot elect to receive cash instead of Ramsay Santé Securities, other than through the Sale Facility described in Section 4.9 of the Demerger Booklet (available only to Small Shareholders, the Ramsay Employee Equity Trustee and Ineligible Overseas Shareholders).
|
See Section 4.4 of the Demerger Booklet for further information
|
| 24. What will my Ramsay Santé entitlement be worth? |
It is not possible to predict the market value of Ramsay Santé Securities following the Demerger, or the combined value of your Ramsay Shares and Ramsay Santé Securities compared to your Ramsay shareholding today. Ramsay Shareholders should not place undue reliance on the current Euronext Paris trading price of Ramsay Santé Shares as an indicator of value after the Demerger given the limited current free float (of approximately 7.39% of shares with 6.67% of this held by one shareholder).
|
See Sections 1 and 4.1 of the Demerger Booklet for further information
|
| Holding and trading your Ramsay Santé Securities |
| 25. What is the practical difference between holding a Ramsay Santé CDI and a Ramsay Santé Share? |
A Ramsay Santé CDI gives you an indirect, beneficial interest in an underlying Ramsay Santé Share, rather than direct legal ownership. CDI holders cannot vote directly at Ramsay Santé shareholder meetings; instead, they instruct CDN (the CDI depositary nominee) how to vote on their behalf. Ramsay Santé CDIs would trade on ASX in Australian dollars; Ramsay Santé Shares trade only on Euronext Paris in Euros.
|
See Section 4.1 of the Demerger Booklet for further information
|
| 26. Do I need a new broker account or CHESS holding to receive or trade my Ramsay Santé Securities? |
No new arrangements are needed simply to receive your Ramsay Santé Securities — holding statements will be sent automatically to the address shown on the Ramsay Share Register. However, if you want to trade Ramsay Santé Shares, you will need a stockbroker or trading platform able to execute trades on Euronext Paris, as not all Australian brokers offer this; Ramsay Santé CDIs, if issued, can be traded on ASX through your existing Australian broker arrangements.
|
See Sections 4.1 and 4.4 of the Demerger Booklet for further information
|
| 27. What price will Ramsay Santé Securities trade at? |
There is no certainty as to the price at which Ramsay Santé Securities will trade following the Demerger. The price will be determined by the market and will depend on many factors, including Ramsay Santé's financial performance, investor demand, broader market conditions and the liquidity of the relevant market on which Ramsay Santé Securities trade.
|
See Section 4.1 of the Demerger Booklet for further information
|
| 28. What will Ramsay Santé’s dividend policy be? |
Ramsay Santé’s dividend policy will be determined by the Ramsay Santé Board at its discretion and may change over time.
|
See Section 3.15.3 of the Demerger Booklet for further information
|
| Small Shareholders and the Sale Facility |
| 29. What happens to my Ramsay Santé entitlement if I am a Small Shareholder? |
If you hold 500 Ramsay Shares or less at the Record Date (a Small Shareholder), the default outcome is cash, not Ramsay Santé Securities. Unless you make a valid election to receive Ramsay Santé Securities, the Ramsay Santé Securities you would otherwise have received will be sold by the Sale Agent under the Sale Facility and the net sale proceeds will be paid to you.
|
See ‘What Ramsay Shareholders should do’ and Section and 4.9 of the Demerger Booklet for further information
|
| 30. Can I choose to receive Ramsay Santé Securities instead of cash? |
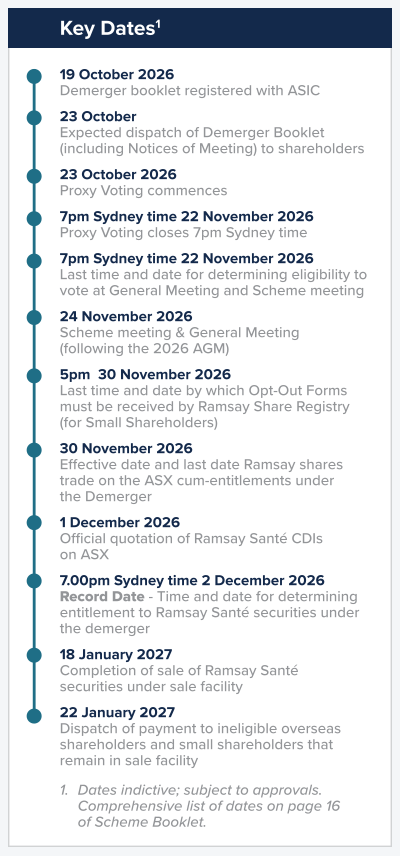
Yes. If you are a Small Shareholder, you can elect to receive Ramsay Santé Securities rather than cash by submitting your Opt-Out Form so that it is received by Ramsay no later than 5.00pm (Sydney time) on 30 November 2026. Please see 4.9 of the Demerger Booklet for further details.
|
See Sections 4.9 and 11 of the Demerger Booklet for further information
|
| 31. What happens if I am a Small Shareholder and I do nothing (except vote)? |
You will receive the net proceeds of the sale of your Ramsay Santé entitlement. No action is required to receive this outcome; you only need to act (by submitting an Opt-Out Form) if you want to receive Ramsay Santé Securities instead.
|
See Section 4.9 of the Demerger Booklet for further information
|
| 32. How is the cash amount I receive calculated, and will I pay any fees? |
The Sale Agent will sell the relevant Ramsay Santé Securities and pay you your share of the proceeds on an averaged basis over all sales under the Sale Facility, so that all Selling Shareholders (which includes Small Shareholders) and Ineligible Overseas Shareholders whose securities are sold, receive the same price per security (subject to rounding down to the nearest whole cent). The amount you receive may be more or less than the price achieved for any particular security and will be after deduction of any brokerage fees, costs or applicable taxes.
|
See Section 4.9 of the Demerger Booklet for further information
|
| Ineligible Overseas Shareholders |
| 33. What if my registered address is outside Australia, New Zealand, the United Kingdom or France? |
You will be an Ineligible Overseas Shareholder and will not receive Ramsay Santé Securities. Instead, the Sale Agent will sell the Ramsay Santé Securities to which you would have been entitled, and the proceeds will be remitted to you, after deduction of any brokerage fees, costs or applicable taxes. You do not need to take any action to receive this outcome.
|
See Sections 4.5 and 4.9 of the Demerger Booklet for further information
|
| CARES holders |
| 34. What if I hold CARES preference shares? |
In accordance with the terms of CARES, CARES holders are not eligible to participate in the Demerger and will not receive Ramsay Santé Securities.
CARES holders are eligible to vote on the Capital Reduction Resolution at the General Meeting but are not eligible to vote on the Supplementary Award Resolution at the General Meeting or Scheme Resolution at the Scheme Meeting.
|
See Section 4.5.5 of the Demerger Booklet for further information
|
| Voting and Meetings |
| 35. What am I being asked to vote on? |
Ramsay Shareholders are being asked to vote on three resolutions: the Capital Reduction Resolution and the Supplementary Award Resolution at the General Meeting, and the Scheme Resolution at the Scheme Meeting. Both the Capital Reduction Resolution and the Scheme Resolution must be passed, along with satisfaction of other conditions, for the Demerger to proceed.
|
See ‘What Ramsay Shareholders should do’ and Section and 4.2 of the Demerger Booklet for further information
|
| 36. What voting majority is required for the Demerger to proceed? |
The Capital Reduction Resolution and the Supplementary Award Resolution require a simple majority (more than 50%) of votes cast. The Scheme Resolution requires both a majority in number (more than 50%) of Ramsay Shareholders voting, and at least 75% of the total votes cast on the resolution.
|
See Section 4.3 of the Demerger Booklet for further information
|
| 37. Who can vote at the Meetings? |
Holders of fully paid ordinary shares in Ramsay who are registered on the Ramsay Share Register at 7.00pm (Sydney time) on 22 November 2026 are eligible to vote on the Capital Reduction Resolution and the Supplementary Award Resolution at the General Meeting and the Scheme Resolution at the Scheme Meeting.
CARES holders who are registered on the Ramsay Share Register at 7.00pm (Sydney time) on 22 November 2026 are eligible to vote on the Capital Reduction Resolution at the General Meeting. |
See Sections 4.3 and 4.5.5 of the Demerger Booklet for further information
|
| 38. How do I vote? |
You can vote in person at the Meetings on 24 November 2026, or lodge a proxy online, by mail or by fax, so that it is received by the Ramsay Share Registry by 7.00pm (Sydney time) on 22 November 2026.
|
See ‘What Ramsay Shareholders should do’ in the Demerger Booklet for more information
|
| 39. What happens if I do not vote? |
If the Demerger Resolutions are passed by the required majorities and the Scheme is approved by the Court, all Ramsay Shareholders will be bound by the outcome, including those who voted against the Scheme and those who did not cast a vote.
|
See Section 4.3 of the Demerger Booklet for further information
|
| Key dates and what happens next |
| 40. When will the Meetings be held? |
The Meetings will be held on 24 November 2026 at The Fullerton Hotel, Sydney, immediately following Ramsay's 2026 Annual General Meeting.
|
See ‘Important dates for Ramsay Shareholders’ in the Demerger Booklet for further information
|
| 41. When is the Record Date? |
The Record Date is 2 December 2026.
|
See ‘Important dates for Ramsay Shareholders’ in the Demerger Booklet for further information
|
| 42. Is the Demerger subject to any conditions? |
The Demerger is subject to the satisfaction or waiver of certain conditions. These include:
- a majority of Ramsay Directors not changing or withdrawing their support for the Demerger;
- Ramsay Shareholders approving the Scheme Resolution by the required majorities at the Scheme Meeting and the Capital Reduction Resolution by the required majority at the General Meeting;
- if the Ramsay Santé Securities are to be issued as Ramsay Santé CDIs, ASX approving quotation of the Ramsay Santé CDIs on ASX (subject to the Scheme becoming Effective and other conditions acceptable to Ramsay);
- regulatory approvals required for the Demerger being obtained; and
- the Court approving the Scheme and the Court order being lodged with ASIC.
The principal conditions and steps to implement the transaction are described further in Section 4.2 of the Demerger Booklet. |
See Section 4.2 of the Demerger Booklet for further information
|
| 43. When will the Demerger be implemented, and when will I receive my holding statement? |
Implementation is expected to occur on 9 December 2026, with holding statements for Ramsay Santé Securities expected to be dispatched to Eligible Shareholders shortly after.
|
See ‘Important dates for Ramsay Shareholders’ in the Demerger Booklet for further information
|
| 44. What happens if the Demerger does not proceed? |
If any condition to the Demerger, including the required shareholder approvals and Court approval, is not satisfied or waived by the End Date, the Demerger will not proceed and Ramsay Shareholders will retain their existing Ramsay Shares, with no change to their holding (and will not receive Ramsay Santé Securities).
|
See Section 4.11 of the Demerger Booklet for further information
|
| Taxation |
| 45. Will I have to pay tax as a result of the Demerger? |
Ramsay has received the Commissioner's draft class ruling on the availability of demerger relief. The class ruling will not be finalised and published until after the implementation of the Demerger. Ramsay Shareholders should review the class ruling once published.
|
See Section 5 of the Demerger Booklet for further information
|
| 46. What are the tax consequences if my Ramsay Santé Securities are sold under the Sale Facility? |
See Section 5.6 of the Demerger Booklet. Ramsay Shareholders should seek independent professional advice having regard to their own circumstances.
|
See Section 5.6 of the Demerger Booklet for further information
|
| 47. Does it make a difference if I hold my Ramsay Shares through an SMSF, company or trust rather than individually? |
Yes. Section 5 of the Demerger Booklet sets out the treatment for each category, and Ramsay Shareholders should seek independent professional advice having regard to their own circumstances.
|
See Section 5 of the Demerger Booklet for further information
|
| 48. Should I obtain my own tax advice? |
Yes. Tax outcomes depend on your individual circumstances, including whether you are an Australian tax resident and whether you hold Pre-CGT or Post-CGT Ramsay Shares. The Demerger Booklet does not constitute tax advice, and Ramsay Shareholders should seek independent professional advice having regard to their own circumstances.
|
See Section 5 of the Demerger Booklet for further information
|
| 49. Is the Dividend assessable? |
If Demerger Tax Relief is available, you will not be assessed on the Dividend.
|
See Section 5.4.1 of the Demerger Booklet
|
| 50. Does the Capital Reduction give rise to CGT consequences? |
Assuming Demerger Tax Relief applies if you choose Demerger Tax Relief, you will be able to disregard any capital gain that arises from the Capital Reduction.
If you do not choose Demerger Tax Relief, a capital gain may arise. You may be entitled to discount CGT treatment on any capital gain if you held your Ramsay Shares for at least 12 months before the Implementation Date.
|
See Section 5.4.2 of the Demerger Booklet
|
| 51. How do you determine the cost base of the Ramsay and Ramsay Santé Securities? |
You must apportion the tax cost base of your Ramsay Shares just before the Demerger between the Ramsay Shares and Ramsay Santé Securities held just after the Demerger.
Further information will be given to you to assist in this apportionment. |
See Section 5.4.4 of the Demerger Booklet
|
| 52. When are you taken to have acquired the Ramsay Santé Securities for CGT discount purposes? |
You may be entitled to the CGT discount on the subsequent disposal of the Ramsay Santé Securities if the Ramsay Santé Securities are taken to have been held for 12 months or more.
For these purposes, you will be treated as having acquired the corresponding Ramsay Santé Securities on the same date as you acquired your Ramsay Shares. |
See Section 5.4.3 of the Demerger Booklet
|
| 53. Does it make a difference if my Ramsay Shares are Pre-CGT Ramsay Shares? |
If you hold Pre-CGT Ramsay Shares:
- no CGT consequences should arise for you in respect of your Pre-CGT Ramsay Shares;
- assuming Demerger Tax Relief applies, if you choose Demerger Tax Relief, you will be able to treat your corresponding Ramsay Santé Securities as pre-CGT assets; and
- if you do not choose Demerger Tax Relief, your tax cost base in your Ramsay Santé Securities will be equal to their market value on the Implementation Date. You will be treated as having acquired your corresponding Ramsay Santé Securities on the Implementation Date
|
See Sections 5.4.2 to 5.4.3 of the Demerger Booklet
|
| 54. What happens if you sell your Ramsay Santé Securities under the Sale Facility? |
The Australian income tax implications of the Demerger outlined in the Demerger Booklet should apply equally to you if your Ramsay Santé Securities are sold by the Sale Agent under the Sale Facility.
You may also make a capital gain or capital loss on the disposal of the Ramsay Santé Securities under the Sale Facility. |
See Section 5.6 of the Demerger Booklet
|
| Further information |
| 55. Where can I get independent advice on what I should do? |
The Demerger Booklet and these FAQs do not constitute financial product advice. If you are in doubt about what to do, you should consult your own financial, legal, taxation or other professional adviser before voting or making any election.
|
See ‘Important information’ in the Demerger Booklet for further information
|